
What Is a Traditional IRA vs a Roth IRA?
The Short Answer
A traditional IRA and a Roth IRA are both retirement accounts, and both hold investments that grow over time. The difference is when you pay tax.
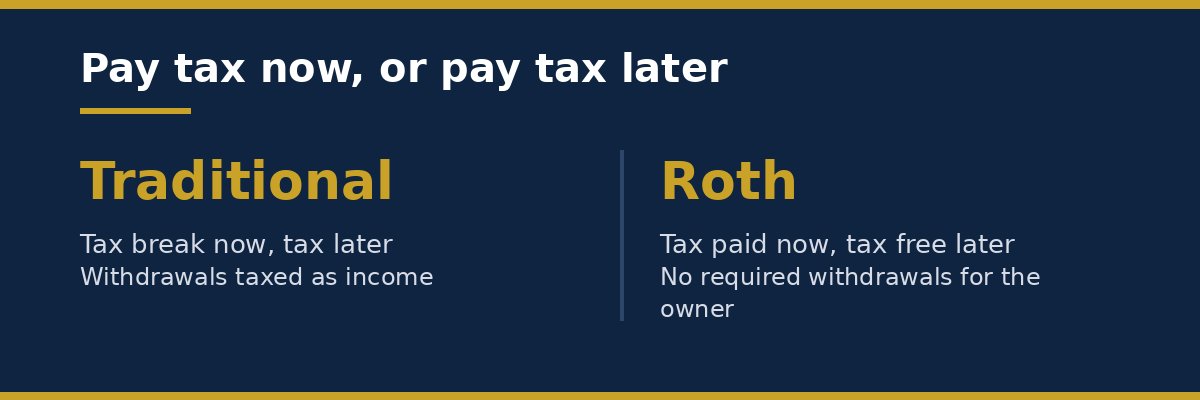
With a traditional IRA, you may get a tax break now, when you put money in, and you pay tax later, when you take money out in retirement. With a Roth IRA, you pay tax now, when you put money in, and you take money out in retirement tax free, if you follow the rules.
So the real question is simple: do you expect your tax rate to be lower now or lower in retirement? If you expect it to be lower in retirement, the traditional IRA may win. If you expect it to be higher later, or you are early in your career with a modest income, the Roth IRA may win. Many people hold one of each over their working life.
What Is a Traditional IRA?
A traditional IRA is an individual retirement account you open yourself, outside your job. You put money in, usually up to a yearly limit set by the IRS, and your investments grow without tax on the growth each year. You pay tax only when you withdraw money in retirement.
Your contribution may be tax deductible, which means it can lower the income you pay tax on this year. Whether you can deduct it depends on your income and whether you or your spouse are covered by a retirement plan at work. For 2026, if you are covered by a plan at work, the deduction phases out between $81,000 and $91,000 of income for single filers, and between $129,000 and $149,000 for married couples filing jointly.
You must start taking required minimum distributions, yearly withdrawals set by the IRS, once you reach the age the rules set, currently 73 for most people. Those withdrawals count as taxable income. You can take money out earlier, but before age 59 and a half you usually pay tax plus a 10 percent penalty, with a few exceptions.
Our guide What Is an IRA in Simple Terms? explains the basics of both types.
What Is a Roth IRA?
A Roth IRA is also an individual retirement account you open yourself. The money you put in has already been taxed, so you get no tax break this year. In return, your investments grow tax free, and withdrawals in retirement are tax free too, as long as you are at least 59 and a half and the account has been open at least five years.
There is no yearly withdrawal rule while you are alive. A Roth IRA has no required minimum distributions for the original owner, so the money can keep growing for as long as you leave it there.
There is one catch: income limits. For 2026, single filers can contribute the full amount below $153,000 of income, a reduced amount between $153,000 and $168,000, and nothing directly at or above $168,000. For married couples filing jointly, the range is $242,000 to $252,000. Earn above the top of the range and you cannot contribute directly to a Roth IRA.
Our guide What Is a Roth IRA? explains the Roth rules in more detail.
The Differences, Side by Side
| Traditional IRA | Roth IRA | |
|---|---|---|
| Tax break | Often now, on contributions | None now |
| Tax on withdrawals | Taxed as income | Tax free, if rules are met |
| Income limit to contribute | None | Yes, phases out at higher incomes |
| Deduction limit | Depends on income and workplace cover | Not applicable |
| Required withdrawals | Yes, from age 73 | None for the original owner |
| Best when | Tax rate may be lower in retirement | Tax rate may be higher in retirement |
The 2026 Limits You Need to Know
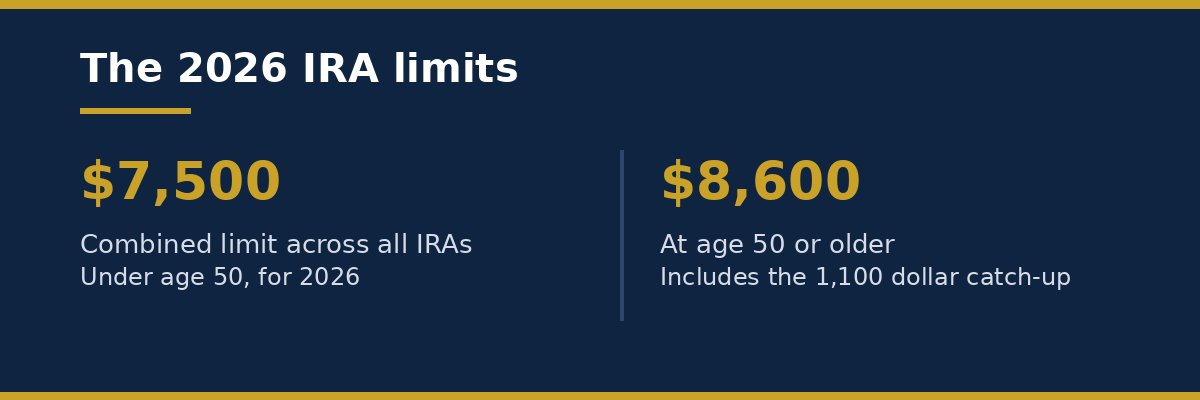
For 2026, the combined limit across all your IRAs is $7,500 if you are under 50, or $8,600 if you are 50 or older, which includes a $1,100 catch-up. This limit is combined, not per account: if you put $5,000 in a Roth IRA, you have only $2,500 of room left for a traditional IRA in the same year.
You also need earned income at least equal to your contribution. If you earned $4,000 in a year, you cannot contribute $7,500. Limits change each year, so check the current IRS figures before you act.
A Worked Example: Same Money, Different Tax Timing
Here is a simple example with round numbers. Suppose you contribute $6,000 to an IRA, and it grows to $12,000 by the time you retire. Assume a 22 percent tax rate in both cases, just to show the timing clearly.
With a traditional IRA, the $6,000 contribution saves you tax now: 22 percent of $6,000 is $1,320. At retirement you withdraw the full $12,000 and pay 22 percent tax on it, which is $2,640. Your after-tax money is $12,000 minus $2,640, which is $9,360, plus the $1,320 you saved at the start, which is $10,680 in total value if you count both.
With a Roth IRA, you pay 22 percent tax on the $6,000 before it goes in, which is $1,320, so $4,680 goes into the account. It grows at the same rate, doubling to $9,360, and you withdraw the full $9,360 tax free.
In this example, with the same tax rate at both ends, the two accounts come out equal in the end: $10,680 of total value for the traditional IRA counting the early tax saving, and $9,360 in the account plus $1,320 already saved for the Roth, which is the same $10,680. The difference appears when the rates differ. If your retirement tax rate is lower than 22 percent, the traditional IRA wins. If it is higher, the Roth IRA wins. That is why the choice is really a guess about your future tax rate.
This example uses a flat rate and ignores fees and other income, so treat it as a teaching example, not a prediction.
Which One Should a Beginner Pick?
Pick the Roth IRA First If…
You are early in your career, your income is modest, and you expect to earn more later. You pay a low tax rate now, and your money grows tax free for decades. A Roth IRA is also more flexible: you can withdraw the money you contributed, but not the growth, at any time without tax or penalty, which can help in a true emergency.
Pick the Traditional IRA First If…
You are in a high tax bracket now and expect a lower income in retirement. The tax deduction this year is worth more to you than tax free withdrawals later. This often fits people in their peak earning years.
Consider Both Over Time
You are not locked in forever. Many people use a Roth IRA early in their career, then add a traditional IRA later when their income rises. You can also split the yearly limit between the two, for example $3,750 in each, as long as the total stays within the $7,500 limit for 2026.
How an IRA Fits With a 401(k)
An IRA is separate from a workplace 401(k). If your employer offers a 401(k) with a match, most beginners take the match first, because it is free money from the employer, and then open an IRA. Our guide What Is a 401(k) Match? explains the match, and What Is a 401(k) in Simple Terms? explains the workplace plan.
A 401(k) has a much higher limit than an IRA, $24,500 for 2026, so it can hold more of your retirement saving. The IRA gives you more control over where the money is invested, because you choose the provider yourself.
Common Mistakes Beginners Make
Contributing More Than the Limit
The $7,500 limit for 2026 is combined across every IRA you own. Putting $7,500 in a Roth IRA and another $7,500 in a traditional IRA breaks the rule and can lead to penalties. Add up all your IRA contributions each year.
Forgetting the Roth Income Limit
A high earner who contributes directly to a Roth IRA above the income limit can face penalties. Check the phase-out range for your filing status before you contribute.
Withdrawing Early Without Knowing the Cost
Taking money out before age 59 and a half usually means tax plus a 10 percent penalty on a traditional IRA, and tax plus penalty on the growth part of a Roth IRA. The Roth lets you withdraw your own contributions any time, but the growth is different. Treat retirement accounts as long term money.
Waiting for the Perfect Choice
Some people delay for years because they cannot decide between traditional and Roth. Either account is far better than no account. Start with your best guess, and you can change the split in later years.
How Much Should You Save?
A common starting target is 15 percent of your income for retirement, including any employer match, once your emergency fund and high interest debt are handled. If 15 percent is too much now, start with what you can afford, even 5 percent, and raise it by 1 percent each year. Our guide How Much Should I Save for Retirement? works through the numbers.
FAQ
Can I have both a traditional IRA and a Roth IRA?
Yes. You can hold both at the same time. The yearly limit is combined, so your contributions to both together must stay within $7,500 for 2026, or $8,600 if you are 50 or older.
Does a Roth IRA have an income limit?
Yes. For 2026, single filers phase out between $153,000 and $168,000 of income, and married couples filing jointly between $242,000 and $252,000. Above the top of the range, you cannot contribute directly. A traditional IRA has no income limit to contribute, though the deduction may be limited.
Is my traditional IRA contribution always tax deductible?
No. If you or your spouse are covered by a retirement plan at work, the deduction phases out above certain incomes. For 2026, the phase-out is $81,000 to $91,000 for single filers covered at work, and $129,000 to $149,000 for married couples filing jointly.
Do I have to take money out of a Roth IRA in retirement?
No, not while you are alive. A Roth IRA has no required minimum distributions for the original owner. A traditional IRA requires yearly withdrawals from age 73.
Can I switch from a traditional IRA to a Roth IRA?
Yes, through a conversion. You move money from a traditional IRA to a Roth IRA and pay tax on the converted amount in that year. The tax bill can be large, so many people convert in a low income year or spread it over several years.
What happens if I contribute too much?
Excess contributions can lead to a 6 percent penalty each year until they are fixed. Check your total across all IRAs each year, and fix an excess promptly, ideally before you file your tax return.
Conclusion
The choice between a traditional IRA and a Roth IRA is a choice about when you pay tax. Pay later, and the traditional IRA may suit you. Pay now, and the Roth IRA may suit you. If you are early in your career with a modest income, the Roth IRA is often the simpler first step. If you are in a high tax bracket and expect less income in retirement, the traditional IRA often wins.
Either way, the account you open and fund beats the one you keep thinking about. Start with your best guess, keep contributions regular, and check the IRS limits each year.
Further reading
This article is for general information and education only. It is not legal or financial advice.
