What is the difference between a checking and a savings account?
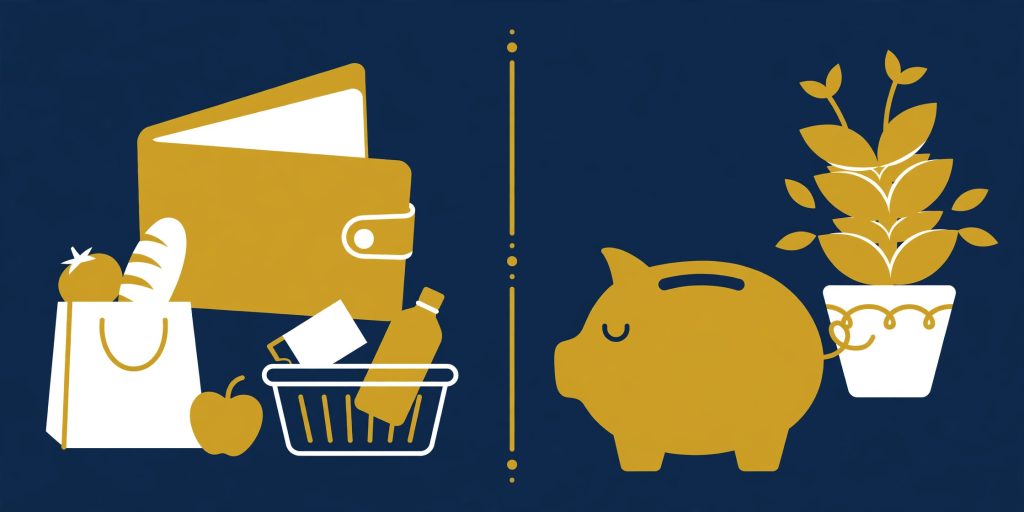
A checking account is for money that moves in and out often. Your pay goes in, and bills, groceries, and everyday purchases go out. A savings account is for money you want to keep separate for a goal or an emergency, where it can earn interest while it waits. Most beginners benefit from having both, with checking as the hub for daily life and savings as the protected reserve.
The simplest way to remember the difference is by job. Checking handles spending. Savings handles keeping. Checking usually comes with a debit card, online bill payment, and frequent transactions. Savings usually earns more interest, is used less often, and is kept apart so it is less tempting to spend. Both are deposit accounts at a bank or credit union, and both can be insured if the institution is insured, which this post explains below.
This post compares the two accounts side by side, shows a worked example of how to split your money, and explains fees, interest, and common mistakes. It is educational only. It is not financial advice, and it does not replace advice from a qualified professional for your own situation.
What a checking account does
A checking account is designed for frequent use. You can receive direct deposit from an employer, pay bills online, write checks if needed, withdraw cash at an ATM, and pay with a debit card. There is no general federal limit on how many checking transactions you can make in a month, because frequent use is the point of the account.
Many checking accounts pay little or no interest. Some do pay interest, but the rate is often low, and the main benefit is convenience, not growth. Checking accounts can also have fees, such as a monthly maintenance fee, an overdraft fee if you spend more than you have, or an ATM fee if you use another bank machine. Some banks waive a monthly fee if you meet a condition, such as a minimum balance or a regular direct deposit, but the conditions vary by bank, so always read the account terms before you open an account.
Checking is also where timing matters most. A bill that is due tomorrow needs money in checking today, not money locked in a separate account that takes two days to transfer. That is why a small buffer in checking, enough to cover bills that have not yet posted, is useful. It reduces the risk of an overdraft fee when a payment and a deposit arrive on different days.
What a savings account does
A savings account is designed for money you plan to keep for a while. You deposit money, it stays separate from daily spending, and it earns interest over time. The interest rate is usually quoted as an annual percentage yield, known as APY, which shows how much interest you would earn in a year if the rate and balance stayed the same. Savings rates vary widely by bank and change over time, so the rate you see today is not a promise for the future.
Savings accounts are often used for an emergency fund, a holiday fund, a home deposit, or another goal that is months away. Keeping goal money in a separate savings account makes progress visible. You can see the balance grow, and you are less likely to spend it by accident when you check your everyday balance.
Some banks set their own rules for savings withdrawals, such as a limit on the number of convenient withdrawals per month, or a fee for extra withdrawals. Other banks have removed those limits. The Federal Reserve removed a federal rule that used to limit certain savings withdrawals to six per month, but individual banks can still set their own limits in their account agreements. Check your bank terms for the exact rule, rather than assuming there is no limit.
Side by side comparison
Use this table as a quick guide, then read the details that follow.
Checking account: main job, everyday spending and bills. How often you use it, daily or weekly. Debit card, usually yes. Interest, often none or low. Best for, pay, bills, groceries, transport, subscriptions. Risk, easy to spend by accident if all your money sits here.
Savings account: main job, keep money for goals and emergencies. How often you use it, occasionally, for deposits and planned withdrawals. Debit card, usually no, or limited. Interest, usually yes, and often higher than checking. Best for, emergency fund, future goals, money you want to protect. Risk, slower access if a transfer takes a day or two, so plan ahead for urgent bills.
Both account types can be held at the same bank, which makes transfers between them easy. Both can also be insured. In the United States, the FDIC insures deposits at FDIC insured banks up to 250,000 dollars per depositor, per insured bank, for each ownership category. This limit was verified from the FDIC. It applies to checking and savings deposits combined in the same ownership category at the same bank, not 250,000 dollars for each account separately. Federally insured credit unions have similar coverage through the NCUA, up to the same 250,000 dollar limit. Insurance protects deposits if the insured institution fails. It does not protect investments such as stocks, bonds, or mutual funds, even if you bought them at a bank.
Worked example: how to split your money
Suppose you take home 2,400 per month after tax. Your monthly bills and everyday spending total 1,800. That leaves 600 for savings and goals. A simple split could be: checking receives the full 2,400 on payday. On the same day, an automatic transfer of 600 moves to savings, leaving 1,800 in checking for bills and spending. That is the pay yourself first method, and it works because savings moves before daily spending can absorb it.
Now split the savings further, if that helps you stay organised. For example, send 300 to an emergency fund savings account and 300 to a holiday or future goal savings account. After three months at this rate, the emergency fund holds 900, and the goal account holds 900, for a total of 1,800 saved, assuming no withdrawals and before interest. After six months, each holds 1,800, for a total of 3,600 saved, again before interest. The interest itself will be small at first, and that is normal. The habit matters more than the first few dollars of interest.
Keep a small buffer in checking as well. For example, if your bills total 1,800, you might aim to keep an extra 200 in checking as a timing buffer, so a bill that posts early does not cause an overdraft. That buffer is part of checking, not part of savings. It is there to handle timing, not to fund a goal. If the buffer drops below your target, top it up from the next pay before you add extra money to a goal.
Which account should you open first?
If you have neither account, open checking first, because you need a place for pay to land and bills to leave from. Then open savings as soon as you can, even if the first deposit is small. The order matters less than having both, with a clear job for each. If you already have checking but no savings, your next step is to open a separate savings account and set an automatic transfer on payday.
When you compare accounts, check five things. First, monthly fees and how to avoid them. Second, overdraft rules and fees for checking. Third, the savings interest rate and whether it is a normal rate or a higher promotional rate. Fourth, how fast you can move money from savings to checking in an emergency. Fifth, whether the bank or credit union is insured, and what the insurance covers. A higher savings rate is useful, but it does not help if fees eat the interest or if transfers are slow when you need the money urgently.
Do not chase a rate alone, and do not open many accounts at once. Two accounts, checking and savings, with clear jobs, are enough for most beginners. You can add a second savings account for a separate goal later, if that helps you stay organised, but each extra account adds another balance to check and another set of terms to remember.
Common mistakes to avoid
The first mistake is keeping everything in checking. When emergency money sits next to spending money, it looks available, and it often gets spent. The second mistake is keeping everything in savings, with too little in checking for bills. That can cause overdraft fees or missed payments when a bill posts before a transfer arrives.
The third mistake is ignoring fees. A checking account with a monthly fee can cost more than the interest you earn on a small savings balance. Read the fee schedule, and ask the bank to explain any term you do not understand before you agree. The fourth mistake is assuming savings interest is fixed. Rates change, so check the rate from time to time, and do not make a long term plan that depends on one rate staying the same.
The fifth mistake is using savings for everyday spending. If you move money from savings to checking every week for groceries, the savings account is not really a savings account, it is a second checking account with slower access. If you find yourself doing this often, your checking budget may be too tight, or your savings transfer may be too large for your current income. Adjust the transfer to an amount you can sustain, and keep savings for goals and emergencies.
Frequently asked questions
Do I need both a checking and a savings account?
Most people benefit from both, but you do not need to open them on the same day. Checking handles daily life. Savings protects goals and emergencies. If you only have one, start with checking, then add savings as soon as you can.
Does a savings account earn more interest than checking?
Usually, yes, but not always, and the difference varies by bank. Many checking accounts pay no interest. Many savings accounts pay interest, and high-yield savings accounts pay more than normal savings accounts. Always check the current rate and terms, because rates change over time.
Can I lose money in a checking or savings account?
Your deposit can be reduced by fees, such as monthly or overdraft fees, and by spending or withdrawals. Insured deposits are protected up to the insurance limit if the insured bank or credit union fails. Insurance does not protect against fees, and it does not protect investments.
How fast can I move money from savings to checking?
It depends on the bank. Some transfers are instant between accounts at the same bank. Transfers between different banks can take one to two business days. If you may need emergency money urgently, check the transfer time before you rely on that account.
Is there a limit on savings withdrawals?
There is no longer a federal rule that limits certain savings withdrawals to six per month, but individual banks can still set their own limits or fees in their account agreements. Check your bank terms for the exact rule that applies to your account.
Should my emergency fund be in checking or savings?
In a separate savings account, in most cases. That keeps it safe, separate from daily spending, and able to earn interest, while still accessible when you need it. Keep only a small timing buffer in checking for bills that have not yet posted.
Conclusion, and your first step today
Checking and savings are partners, not competitors. Checking moves money for daily life. Savings keeps money for the future. Open checking first if you have neither, add a separate savings account next, set an automatic transfer on payday, and keep a small buffer in checking for timing. Today, check one thing: do you have a separate savings account, and is your emergency money separate from your spending money? If not, that is your next step.
Your next steps in this series are: how much to keep in an emergency fund, when to use a high-yield account versus a normal savings account, and whether your money is safe in a bank and what insurance means. Those posts link here in the Saving and Banking cluster once they are published.
Disclaimer: This article is for education only. It is not financial advice, and it does not guarantee any result. Your income, costs, debts, and goals are personal, and you should consider your own situation, and speak to a qualified professional if you need personal advice, before making a financial decision.