How much should I keep in an emergency fund?
Start with a small starter fund you can reach soon, then build toward three to six months of essential expenses. Essential expenses are the bills you must still pay if your income stops for a while, such as rent or mortgage, utilities, food at home, insurance, transport to work, and minimum debt payments. They do not include dining out, streaming, new clothes, or other wants you could pause in a real emergency.
For many beginners, three months of essential expenses is a solid first full target. Six months may be a better target if you are the only earner in your home, if your income changes from month to month, if you are self employed, or if finding a similar job would take a long time. There is no single number that fits every household, and no law or regulator sets one required amount for everyone. The right amount depends on your costs, your income stability, and how many people depend on that income.
This post shows how to calculate your own number, how to choose between three months and six months, and how to build the fund in stages so the goal does not feel impossible. It is educational only. It is not financial advice, and it does not replace advice from a qualified professional for your own situation.
What counts as an essential expense?
An essential expense is a cost that keeps a roof over your head, food on the table, and your basic life running. Start with housing, then utilities, then food at home, then insurance, then transport you need for work or essential travel, then minimum payments on debts, then phone and internet if you need them for work or safety, and then childcare if you rely on it to work. Add these up for a normal month. That total is the base for your emergency fund math.
Do not use your total spending, and do not use your gross pay. Total spending includes wants you could cut in an emergency, so it can make the target look larger than it needs to be. Gross pay includes tax you never receive, so it can also distort the target. Essential expenses are the honest middle ground. They show what you would need to keep going while you look for work, wait for a repair, or handle a medical bill.
One useful test is to ask, for each item, would I still have to pay this if I lost my income tomorrow? If the answer is yes, include it. If the answer is no, or if you could pause it without harm, leave it out of the emergency fund calculation. You can still save for wants and goals separately, but the emergency fund has a clear job, and that job is essentials.
How to calculate your number in five minutes
First, list your essential monthly expenses with real amounts from your bank statements or bills, not guesses. Second, add them up to get one monthly essential total. Third, multiply that total by three for a three month target, and by six for a six month target. That range is your planning range. Fourth, pick a starting target inside that range based on your situation, which the next section explains. Fifth, subtract what you already have saved for emergencies, if anything, to see how much is left to build.
Here is a worked example with simple numbers. Suppose your essential monthly expenses are rent 900, utilities 150, food at home 300, insurance 120, transport to work 130, minimum debt payments 200, and phone and internet 100. Add them up: 900 plus 150 equals 1,050, plus 300 equals 1,350, plus 120 equals 1,470, plus 130 equals 1,600, plus 200 equals 1,800, plus 100 equals 1,900. Your monthly essential total is 1,900.
Now multiply. Three months is 1,900 times 3, which equals 5,700. Six months is 1,900 times 6, which equals 11,400. So this household has a planning range of 5,700 to 11,400. If you already have 1,000 saved for emergencies, the amount left to reach three months is 5,700 minus 1,000, which equals 4,700. The amount left to reach six months is 11,400 minus 1,000, which equals 10,400. Do the same math with your own numbers, and write the result down where you can see it.
Should you aim for three months or six months?
Three months is often enough as a first full target if you have stable work, two incomes in the home, a job that is easy to replace, or other support you can rely on in a short crisis. It gives you breathing room for a car repair, a medical bill, or a short gap in income, without asking you to save for years before you feel safe.
Six months, or more, is worth considering if you are the only earner, if you are self employed or freelance, if your income is irregular, if you support children or other family members, if you have a health condition that could limit work, or if your field has long hiring times. In those cases, a longer runway can reduce pressure and reduce the chance that a short emergency turns into long term debt.
If six months feels too far away, do not let that stop you. Aim for a starter fund first, then one month of essentials, then three months, then six months. Each stage is real progress. A starter fund of 500 to 1,000 can cover many small emergencies, such as a tire repair or a broken appliance, without a credit card. One month of essentials gives you a full month to solve a problem. Three months gives you time to find work. The stages matter because they keep you moving instead of waiting for a perfect amount.
Where should you keep the money?
Keep an emergency fund in a safe place you can reach quickly, but not so easily that you spend it on everyday wants. For most beginners, a separate savings account at an insured bank or credit union is a good fit. The Consumer Financial Protection Bureau, known as the CFPB, advises keeping emergency savings safe, accessible, and in a place where you are not tempted to spend it on non emergencies. A separate account, clearly named Emergency Fund, helps with all three points.
Check that the account is insured. In the United States, deposits at FDIC insured banks are covered up to 250,000 dollars per depositor, per insured bank, for each ownership category, as confirmed by the FDIC. Deposits at federally insured credit unions have similar coverage through the National Credit Union Administration, known as the NCUA, up to the same 250,000 dollar limit per depositor, per credit union, for each ownership category. Insurance protects you if the insured bank or credit union fails. It does not protect money invested in stocks, bonds, or mutual funds, even if you bought them at a bank.
Do not keep the full fund in cash at home, and do not keep it in investments that can fall in value right when you need the money. Cash at home can be lost or stolen, and it earns nothing. Investments can be down when an emergency arrives, which forces you to sell at a bad time. A savings account is boring on purpose. Its job is to be there, in full, when you need it.
A simple plan to build it, even on a tight budget
Start with an amount you can keep every payday, even if it is small. A fixed transfer on payday works better than waiting to see what is left at the end of the month, because what is left is often nothing. If your pay is weekly, move a small amount weekly. If your pay is monthly, move it on payday. Automatic transfers help because they remove the daily decision.
Next, use windfalls with a plan. When you get a tax refund, a bonus, a gift, or money from selling something you no longer need, send a set share to the emergency fund before you spend the rest. For example, you could send half of a windfall to the fund and use the rest for bills or a small reward. The CFPB suggests saving all or part of windfalls, and this simple rule makes that advice practical.
Then, review your progress once a month. Check the balance, compare it to your target, and adjust the transfer if your income or expenses changed. If you had to use the fund, do not feel guilty. That is what it is for. Rebuild it with the same small, steady transfer, starting with the next payday. A fund that is used and rebuilt is doing its job.
Here is a worked timeline using the example above, where the three month target is 5,700 and you start with 1,000 already saved. You still need 4,700. If you save 200 per month, you divide 4,700 by 200, which equals 23.5 months, so about 24 months to reach three months of essentials. If you save 300 per month, you divide 4,700 by 300, which equals about 15.7 months, so about 16 months. If you add a 1,000 tax refund in year one, the remaining amount falls to 3,700, and at 300 per month that takes about 12.3 months, so about 13 months after the refund. The math is simple, and it shows why both a steady transfer and an occasional windfall help.
Mistakes that make an emergency fund fail
The first mistake is setting a target so large that you never start. If six months feels impossible, start with 500, then one month, then three months. Progress beats perfection. The second mistake is keeping the fund in your checking account, where it looks like spending money. A separate account with a clear name reduces accidental spending.
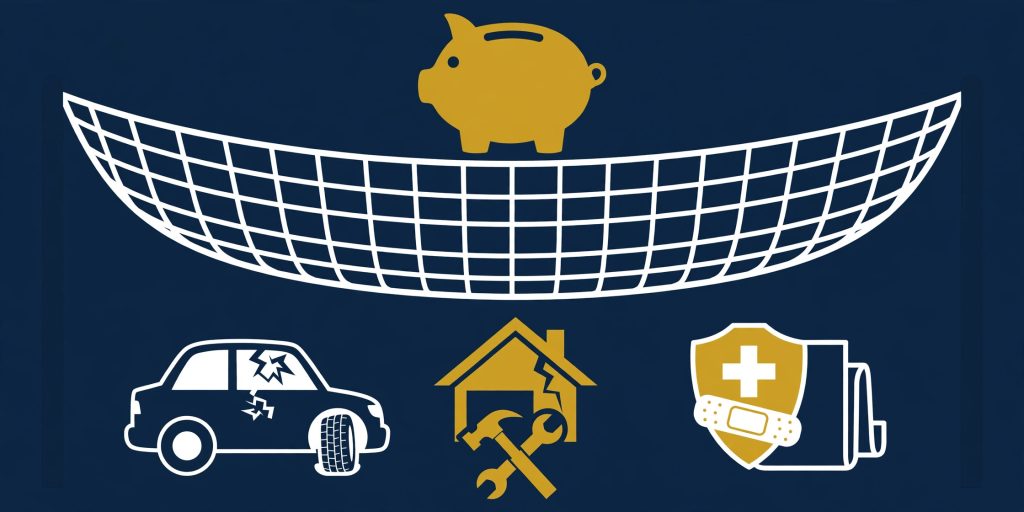
The third mistake is having no rules for when to use it. Write down your rules in advance. For example, job loss, urgent medical care, urgent car repair needed for work, and urgent home repair that affects safety or habitability all count. A sale, a holiday, a new phone, or a gift does not count, even if it feels urgent in the moment. Clear rules make the decision easier when stress is high.
The fourth mistake is stopping after one emergency. Emergencies happen more than once. The Federal Reserve found in its 2025 household survey, published in May 2026, that 59 percent of adults had at least one major unexpected expense in the prior 12 months. That is why rebuilding matters as much as building. After you use the fund, restart the automatic transfer right away, even at a smaller amount, and build back in stages.
Frequently asked questions
Is three months always enough?
Not always. Three months is a common planning guide, not a guarantee. It may be enough if your income is stable and your job is easy to replace. If your income is irregular, if you are the only earner, or if finding work takes a long time, aim higher, toward six months or more.
Should I count my full salary or my essential expenses?
Count essential expenses, not your full salary and not your full lifestyle spending. Essential expenses show what you must pay to keep going in a crisis. Using full spending can inflate the target, and using gross pay can include tax you never receive.
What if I have debt and no emergency fund?
Do not ignore either one. Keep making minimum debt payments, and build a small starter fund at the same time, if you can do so without missing a minimum payment or an essential bill. A small fund can prevent a new emergency from becoming new debt. Then, once the starter fund is in place, you can balance extra debt payments with building the full fund. The debt payoff posts in this series explain that balance in more detail.
Can I keep my emergency fund in a high-yield savings account?
Yes, if the account is at an insured bank or credit union and you can withdraw the money quickly when you need it. A high-yield savings account is a savings account that pays a higher interest rate than a normal savings account. Check the current rate, any fees, and how fast you can transfer money to your checking account in an emergency, because those details change over time.
What counts as a real emergency?
A real emergency is unexpected, necessary, and urgent. Job loss, urgent medical care, a car repair you need to get to work, and a home repair that affects safety are common examples. A planned expense, a sale, or a want you can delay is not an emergency, even if it is tempting.
How fast should I build the fund?
As fast as you can sustain without missing essential bills or minimum debt payments. A steady amount every payday is better than a large amount once that you cannot repeat. If you can increase the transfer later, when income rises or a debt is paid off, do that, and update your target at the same time.
Conclusion, and your first step today
Your emergency fund number is not a mystery. Add up your essential monthly expenses, multiply by three and by six, and pick a starting stage you can reach. Then open or name a separate insured savings account, set an automatic transfer for payday, and write down your rules for using the fund. Today, do just the math. Find your essential monthly total, write down your three month and six month targets, and choose your first stage, starter fund, one month, or three months.
Your next steps in this series are: how to build an emergency fund from zero, when to use a high-yield account versus a normal savings account, and whether your money is safe in a bank and what insurance means. Those posts link here in the Saving and Banking cluster once they are published.
Disclaimer: This article is for education only. It is not financial advice, and it does not guarantee any result. Your income, costs, debts, and goals are personal, and you should consider your own situation, and speak to a qualified professional if you need personal advice, before making a financial decision.